How to Pay Off a Hard Money Loan With a DSCR Loan?
See how to pay off a hard money or private loan, and obtain a long term mortgage.
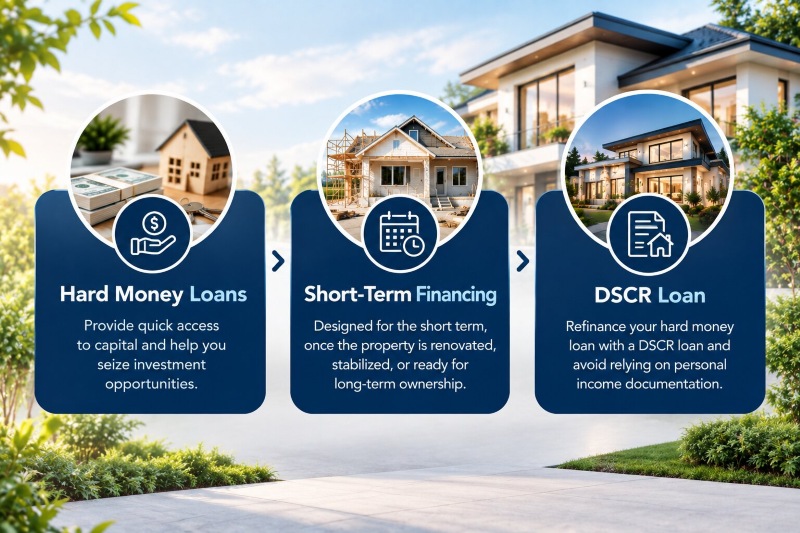
Hard money loans can be a valuable financing tool for real estate investors. They can provide quick access to capital, help investors purchase properties that may not qualify for traditional financing, and give borrowers the flexibility to move quickly when an investment opportunity arises.
However, hard money loans are generally designed as short-term financing. Once the property has been purchased, renovated, stabilized, or otherwise positioned for long-term ownership, an investor may want to replace the hard money loan with longer-term financing.
One option to consider is a DSCR loan. For qualified investment properties, a DSCR loan may allow an investor to refinance the existing hard money loan and pay it off without relying primarily on personal income documentation.
What Is a Hard Money Loan?
A hard money loan is typically a short-term loan secured by real estate. Unlike conventional mortgages, hard money lenders often place greater emphasis on the value of the property and the investment opportunity than on the borrower's traditional income documentation.
Hard money financing can be particularly useful when an investor needs to close quickly or when a property requires improvements before it will qualify for conventional financing.
The tradeoff is that hard money loans often have higher interest rates, shorter terms, and potentially higher fees than traditional investment-property financing. A loan may have a term of 12 months or less, depending on the lender and transaction.
For an investor who intends to hold the property as a rental, continuing to carry short-term financing may not be the ideal long-term strategy.
What Is a DSCR Loan?
DSCR stands for Debt Service Coverage Ratio. A DSCR loan is an investment property loan that primarily looks at the property's ability to generate enough rental income to cover its debt obligations.
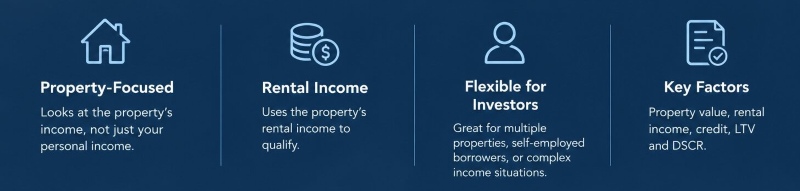
Instead of focusing exclusively on the borrower's personal income, the lender evaluates the property's income and expenses as part of the qualification process.
For more information, on No Income Verification Loan Options, click here.
This can make DSCR financing particularly appealing to real estate investors who own multiple properties, are self-employed, or have income that may be more complicated to document through traditional mortgage underwriting.
The specific requirements vary by lender, but factors such as the property's value, rental income, credit profile, loan-to-value ratio, and debt service coverage ratio can all play a role.
How Does Paying Off a Hard Money Loan With a DSCR Loan Work?
The basic concept is relatively straightforward. An investor purchases a property using a hard money loan. After the property has been renovated or stabilized, or simply once the investor determines that long term financing makes more sense, the investor applies for a DSCR refinance.
If the investor and property meet the underwriting requirements, the new DSCR loan is used to pay off the existing hard money loan.
For example, suppose an investor purchased an investment property for $400,000 and used hard money financing to complete the acquisition and improvements. After renovations, the property is worth $500,000 and is being rented to a qualified tenant.
If the investor has sufficient equity and the property meets the DSCR lender's requirements, a DSCR refinance could potentially replace the hard money loan with longer-term financing.
The exact loan amount, interest rate, costs, and cash out availability will depend on the lender and the individual transaction.
Why Would an Investor Refinance a Hard Money Loan?
There are several reasons an investor may consider moving from hard money to DSCR financing.
Lower monthly financing costs: Depending on market conditions and the specific loans involved, a DSCR loan may provide a lower interest rate than the investor's existing hard money loan. Some investors may choose to have an interest only mortgage payment to increase their positive cashflow on the property.
Longer term financing: Hard money loans are generally intended to be temporary. A DSCR mortgage can provide a longer-term financing solution for an investor who plans to hold the property as a rental.
Property stabilization: An investor may initially use hard money because the property needs renovations or does not yet fit the requirements of a traditional investment loan. Once the work is complete and the property is generating rental income, refinancing may become more practical.
Less emphasis on personal income: DSCR financing can be attractive to investors whose personal income does not fit neatly into traditional mortgage underwriting. Qualification can be based substantially on the property's ability to support the proposed debt.
Potential to preserve capital: Depending on the transaction and available equity, refinancing may allow an investor to pay off the hard money lender while potentially recovering some of the capital invested in the property.
What Does an Underwriter Need to See?
Although DSCR loans can have more flexible income requirements than conventional financing, they are not automatic approvals.
The underwriter will typically evaluate the property and borrower based on several factors. These can include the property's current value, rental income, the proposed monthly debt payment, credit history, available equity, and the loan to value ratio.
The property's rental income is particularly important because the DSCR calculation helps determine whether the property generates sufficient income to support its debt obligations.
The lender may also consider the type of property, whether it is occupied, the lease or market rent, and other characteristics of the investment.
Timing Is Important
Investors should not wait until the last minute to consider refinancing a hard money loan.
Because hard money financing is often short-term, it is important to begin evaluating the refinance well before the maturity date. The investor may need an appraisal, title work, documentation, underwriting and other steps before the new loan can close.
Starting the process early can also give the investor time to address potential issues, such as insufficient equity, credit concerns, property condition, or rental-income considerations.
In some situations, an investor may discover that the property does not yet qualify for the desired DSCR loan. Identifying that early provides more time to consider alternatives.
A hard money loan can be an effective way to acquire and improve an investment property, but it is generally not intended to be permanent financing. For investors who want to keep a property as a long term rental, refinancing the hard money loan with a DSCR loan may provide an opportunity to transition to longer-term investment-property financing.
The key is to plan ahead. Evaluating the property's value, rental income, equity position, credit profile, and anticipated financing costs can help determine whether a DSCR refinance is a practical solution.
If you currently have a hard money loan that is approaching maturity, it may be worthwhile to discuss your situation with a mortgage professional who works with investment property financing. A review of the property and existing loan can help determine whether a DSCR refinance could be used to pay off the hard money loan and provide a more suitable long term financing strategy.
For more information on obtaining a DSCR loan, please contact us to discuss your real estate financing needs.
Mortgage Insight:
Purchasing a Home with a Conventional Loan
VA Loan Success Story with Eric and Denise
How a VA Loan in Ocala, FL changed a Family's Financial Future
Can I Use My VA Loan in a Chapter 13 Bankruptcy?
Can a Fiance or Kids be on a VA Loan?
Veterans Who Buy Homes See Far Higher Net Worth Than Renters
How Much Mortgage Insurance Can I Save with a VA Loan?
Duplex Property in Fort Lauderdale Quadruples in Value and Leaves a Nest Egg to the Heirs
How a California Remote Worker Obtained a Mortgage to Relocate to Boca Raton, FL
What's the Average Mortgage in Fort Lauderdale, FL?
What Factors are in my Credit Score for a Mortgage?
What Documents Do You Need for a No Income Verification Mortgage?
Restaurant Owner Obtains Self-Employed Home Loan
Can a General Contractor Obtain a No Income Verification Mortgage?
Is a HELOC or a Cash Out Refinance Better to Pay for a New Roof?
Can a Collection Prevent Me from Getting a Mortgage?
Do I Have to Make Mortgage Payments if I Lose My Job?
How to Rent Out Your Investment Property
How Private Money Works in Real Estate Investing
What Portion of a Mortgage Payment Goes Towards Insurance
How Much Cash Can I Take Out of My Home?
Top 5 Purposes for a Cash-Out Refinance
Is My VA Disability Income Enough for a VA Loan?
Can I Use a VA Loan More Than One Time?
Helping Renters Build Credit with These 4 Strategies
How to Get a Mortgage Pre-Approval Letter
What Fannie Mae’s Crypto Move Means for Homebuyers?
Can a Canadian Citizen Get a U.S. Mortgage?
What to Know When Purchasing a Duplex with a Mortgage
Can Refinancing Your Car Help You Qualify for a Mortgage?
How Business Owners Can Qualify for an Interest Only Home Loan?
Your mortgage journey.
Various loan type options including:
Conventional loan
FHA loan
VA loan
Self-employed loan options
No income verification for investors
Benefits of Homeownership
Homeownership is a significant milestone and a decision that offers many advantages. In addition to providing a place to call your own, owning a home brings financial stability, personal fulfillment, and a sense of belonging. Mortgage Group has been helping individuals and families obtain homeownership, guiding them through the process and obtaining referrals to help their family and friends accomplish the same.
Purchase
Get pre-approved to purchase your first home, second home or upcoming investment property.
Refinance
Own a property and interested in lowering your payment? Need to take cash out? Refinance with confidence.
Connect with Us
Our experienced team with be happy to speak with you, and walk you through each step of the process.
Providing mortgage solutions to help you with your home.
Mortgages can be complicated and have many moving parts. Let our team help you!
Contact Us
It only takes a few moments to reach out and have an initial conversation.
Know the Next Steps
Our team will work with you to find the best way to achieve your home loan goals.
Find Your Home and Get Your Loan
Our team will be prepared to move with the next steps once you have secured your home purchase contract.
Houses
Townhomes
Condos
Multi-Units
Contact our team today.
1-800-583-5305
© Copyright 2026 E Mortgage Capital, Inc.. All rights reserved.
- 1416824 | E Mortgage Capital, Inc.
Notice To Texas Loan Applicants: Consumers wishing to file a complaint against a mortgage banker, or a licensed mortgage banker residential mortgage loan originator, should complete and send a complaint form to the Texas Department of Savings and Mortgage Lending, 2601 North Lamar, Suite 201, Austin, TX 78705. Complaint forms and instructions may be obtained from the department’s website at www.sml.texas.gov
A toll-free consumer hotline is available at 1-877-276-5550. The department maintains a recovery fund to make payments of certain actual out of pocket damages sustained by borrowers caused by acts of licensed mortgage banker residential mortgage loan originators. A written application for reimbursement from the recovery fund must be filed with and investigated by the department prior to the payment of a claim. For more information about the recovery fund, please consult the department’s website at
www.sml.texas.gov